1. The UPI Micro-Transaction Trap: Death by 1,000 QR Codes
Consider a standard Tuesday in the life of an urban Indian salaried professional:
- ₹20 for morning cutting chai (UPI to local vendor)
- ₹180 for quick breakfast via Swiggy Instamart (UPI debit)
- ₹140 for cab to work via Uber (PhonePe auto-pay)
- ₹450 for lunch with colleagues (Split bill on Google Pay)
- ₹350 evening pharmacy purchase (Apollo 24|7 card swipe)
- ₹1,200 dinner grocery run on Blinkit (Credit card reward points)
Individually, not a single one of these expenses raises an alarm. Yet by the 25th of the month, your bank balance is depleted by ₹40,000 more than you anticipated.
Because physical paper notes have all but disappeared, the biological pain of parting with cash has been completely erased. You tap a finger, see a green tick, and move on.
2. Why Manual Logging & Excel Spreadsheets Always Fail
Almost everyone tries the spreadsheet route at least once. You create columns for Date, Merchant, Category, and Amount. On day one, you log faithfully. By day four, you forgot two auto-rickshaw rides. By day ten, you have 18 unlogged UPI payments and the emotional friction of catching up feels like an unpaid tax audit. You abandon the sheet.
A habit that relies on manual willpower will always fail under cognitive fatigue. The only sustainable expense management system is one that captures data at the exact point of transaction automatically—without requiring you to open the app or remember receipts.
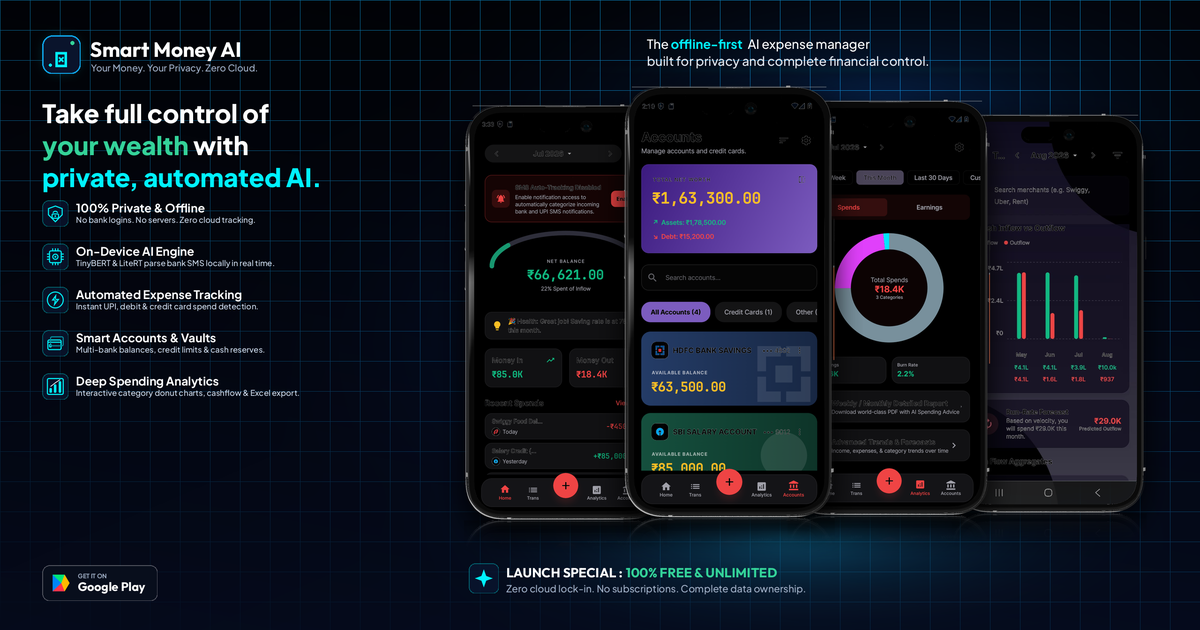
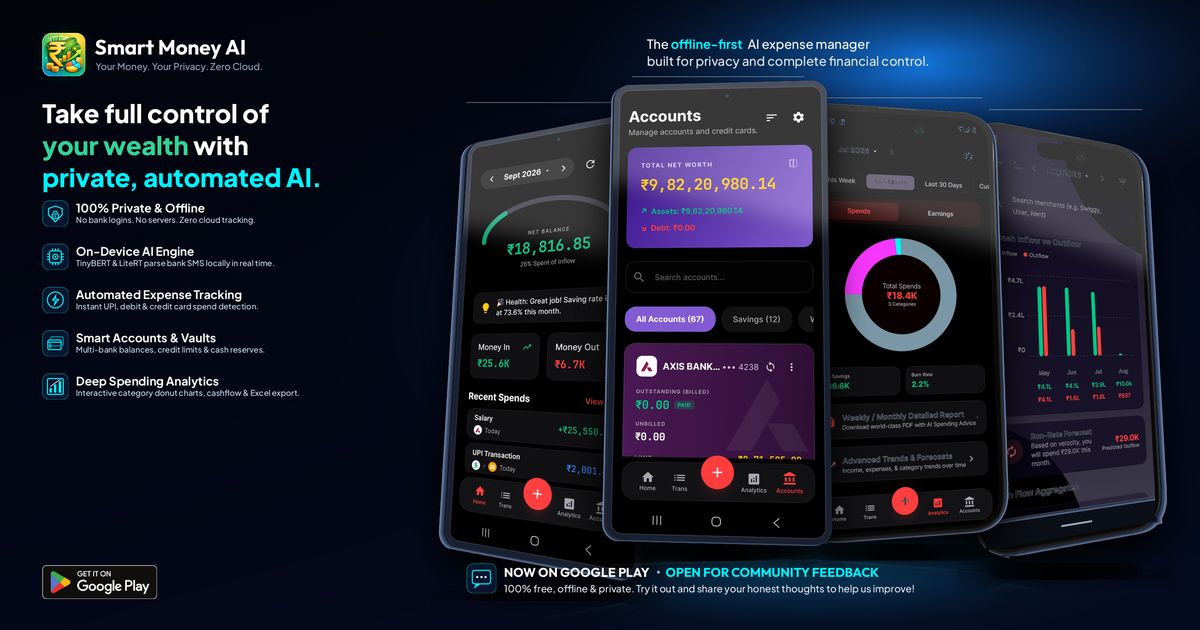
This is why automated notification parsing in Smart Money AI transforms financial health. The app silently captures the alert, matches the merchant to a predefined category, adjusts your account balances, and gives you instant visibility.
3. Setting Up Your Digital Vaults Architecture
To gain financial clarity, your money should be segmented into clear operational buckets rather than pooled in one messy account. Here is the recommended 3-Vault framework:
-
Vault 1: The Salary / Inflow Hub (e.g. HDFC or ICICI Bank)
Where your salary lands, mutual fund SIPs are debited, and fixed bills (rent, EMIs, insurance) are scheduled. Avoid linking your primary UPI scanner to this account. -
Vault 2: The UPI Daily Spending Vault (e.g. SBI or Kotak 811)
A dedicated secondary account loaded with a strict monthly allowance (e.g. ₹15,000). Link your PhonePe and Google Pay accounts exclusively here. If your UPI balance reaches zero, your discretionary spending stops. -
Vault 3: The Strategic Credit Card Vault (e.g. Axis Atlas, SBI Cashback, Amazon Pay ICICI)
Used only for high-ticket online purchases, flight tickets, and electronics where rewards and buyer protection apply.
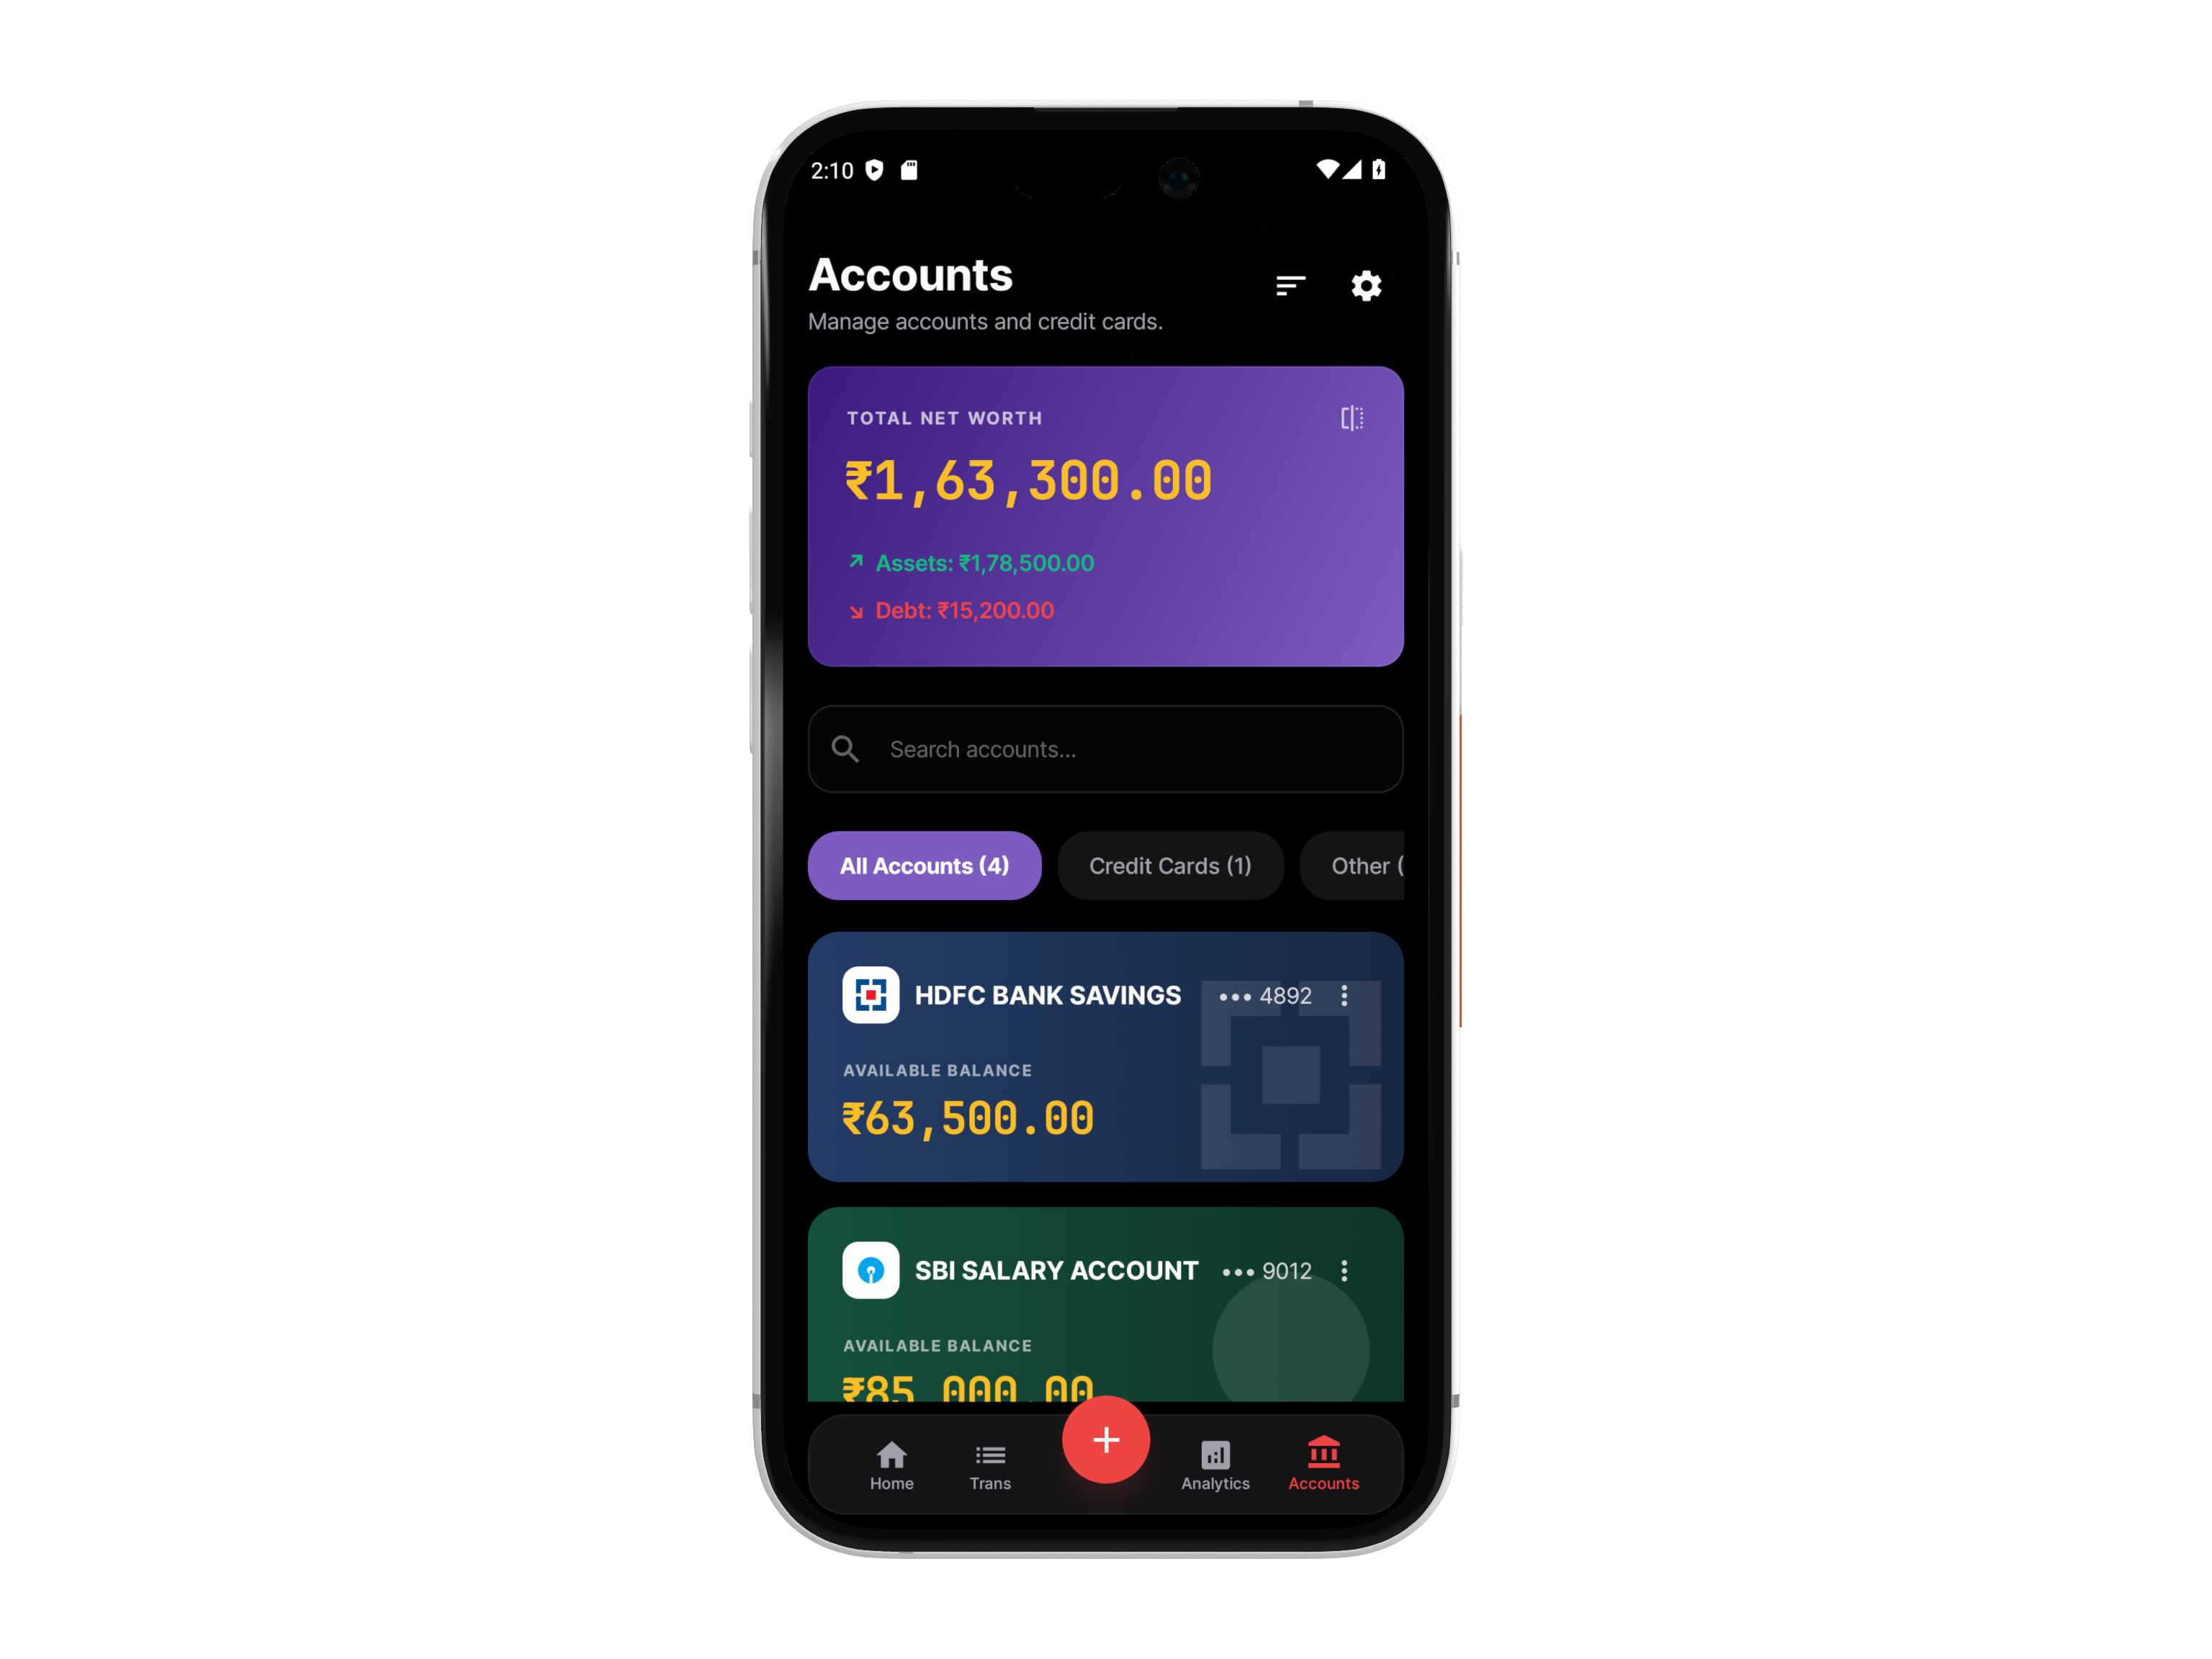
In Smart Money AI, each vault displays its authentic bank brand badge, real-time balance, and transaction history.
4. Taming Credit Card Cycles & Debt Limits
Credit cards are powerful wealth-building tools when used properly, but dangerous when mismanaged. The secret to keeping a credit score above 780 lies in your Credit Utilization Ratio (CUR).
Credit bureaus (CIBIL, Experian) penalize borrowers who utilize more than 30% of their sanctioned limit. If your card limit is ₹2,00,000, your outstanding balance on statement generation date should never exceed ₹60,000.
Smart Money AI's Credit Card Vault allows you to enter your total credit limit. Every time an SMS confirmation arrives from ICICI, HDFC, or Axis, your current outstanding debt and available limit are recalibrated automatically, warning you well before you reach high-utilization thresholds.
5. The Safe Daily Spend Strategy
One of the most praised features in Smart Money AI's v2.1 update is the Safe Daily Spend Calculator, displayed on the compact budget status bar:
Safe Daily Spend = (Monthly Budget Limit - Total Spent to Date) / Days Remaining in Month
Rather than telling you an abstract number like "You spent ₹32,450 this month", Smart Money AI translates your financial reality into actionable daily pacing:
- "You have 12 days left this month. Your safe daily spend is ₹1,120/day."
- If you splurge on a ₹3,000 dinner tonight, tomorrow's safe daily spend automatically adjusts downward to ₹950/day.
This dynamic feedback loop prevents the dreaded end-of-month panic without forcing you into rigid austerity.
6. The 2-Minute Weekly Wealth Arc Review
You don't need to obsess over your finances every hour. We recommend a dedicated 2-minute audit every Sunday evening using the Wealth Arc:
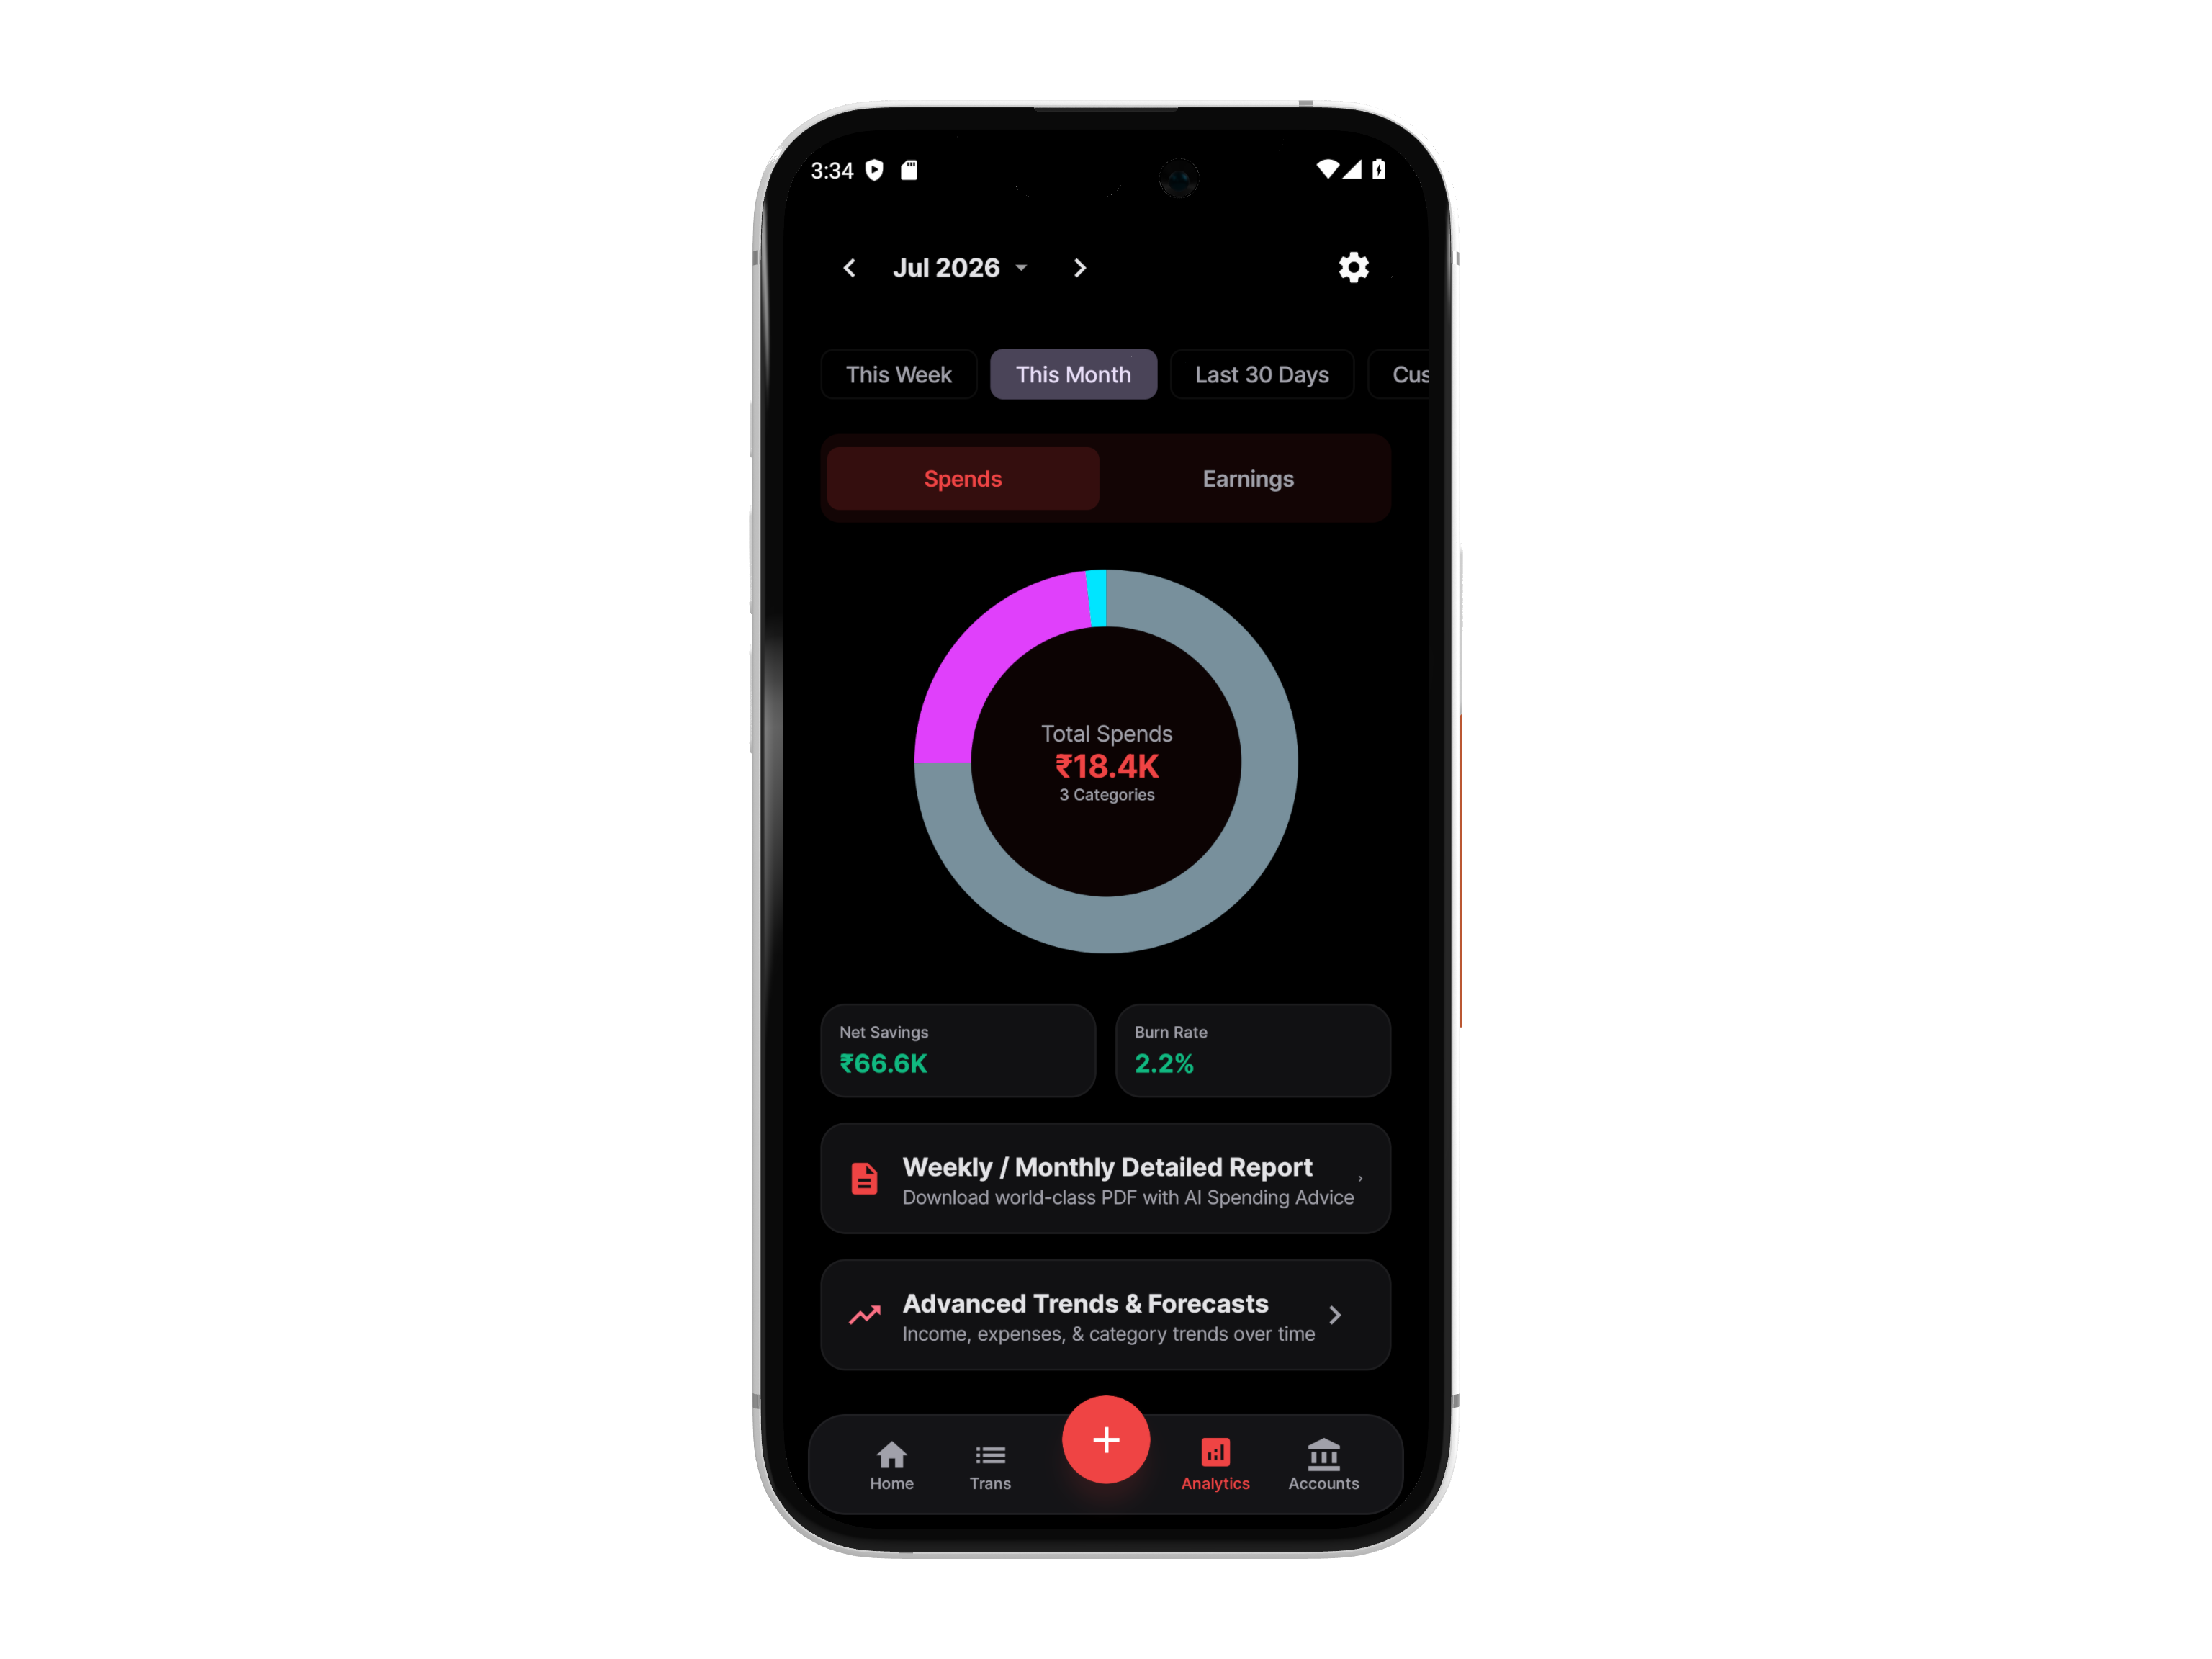
- Open Smart Money AI (unlocked instantly with your biometric fingerprint).
- Inspect the Wealth Arc: Is the green inflow arc comfortably wider than the red outflow arc?
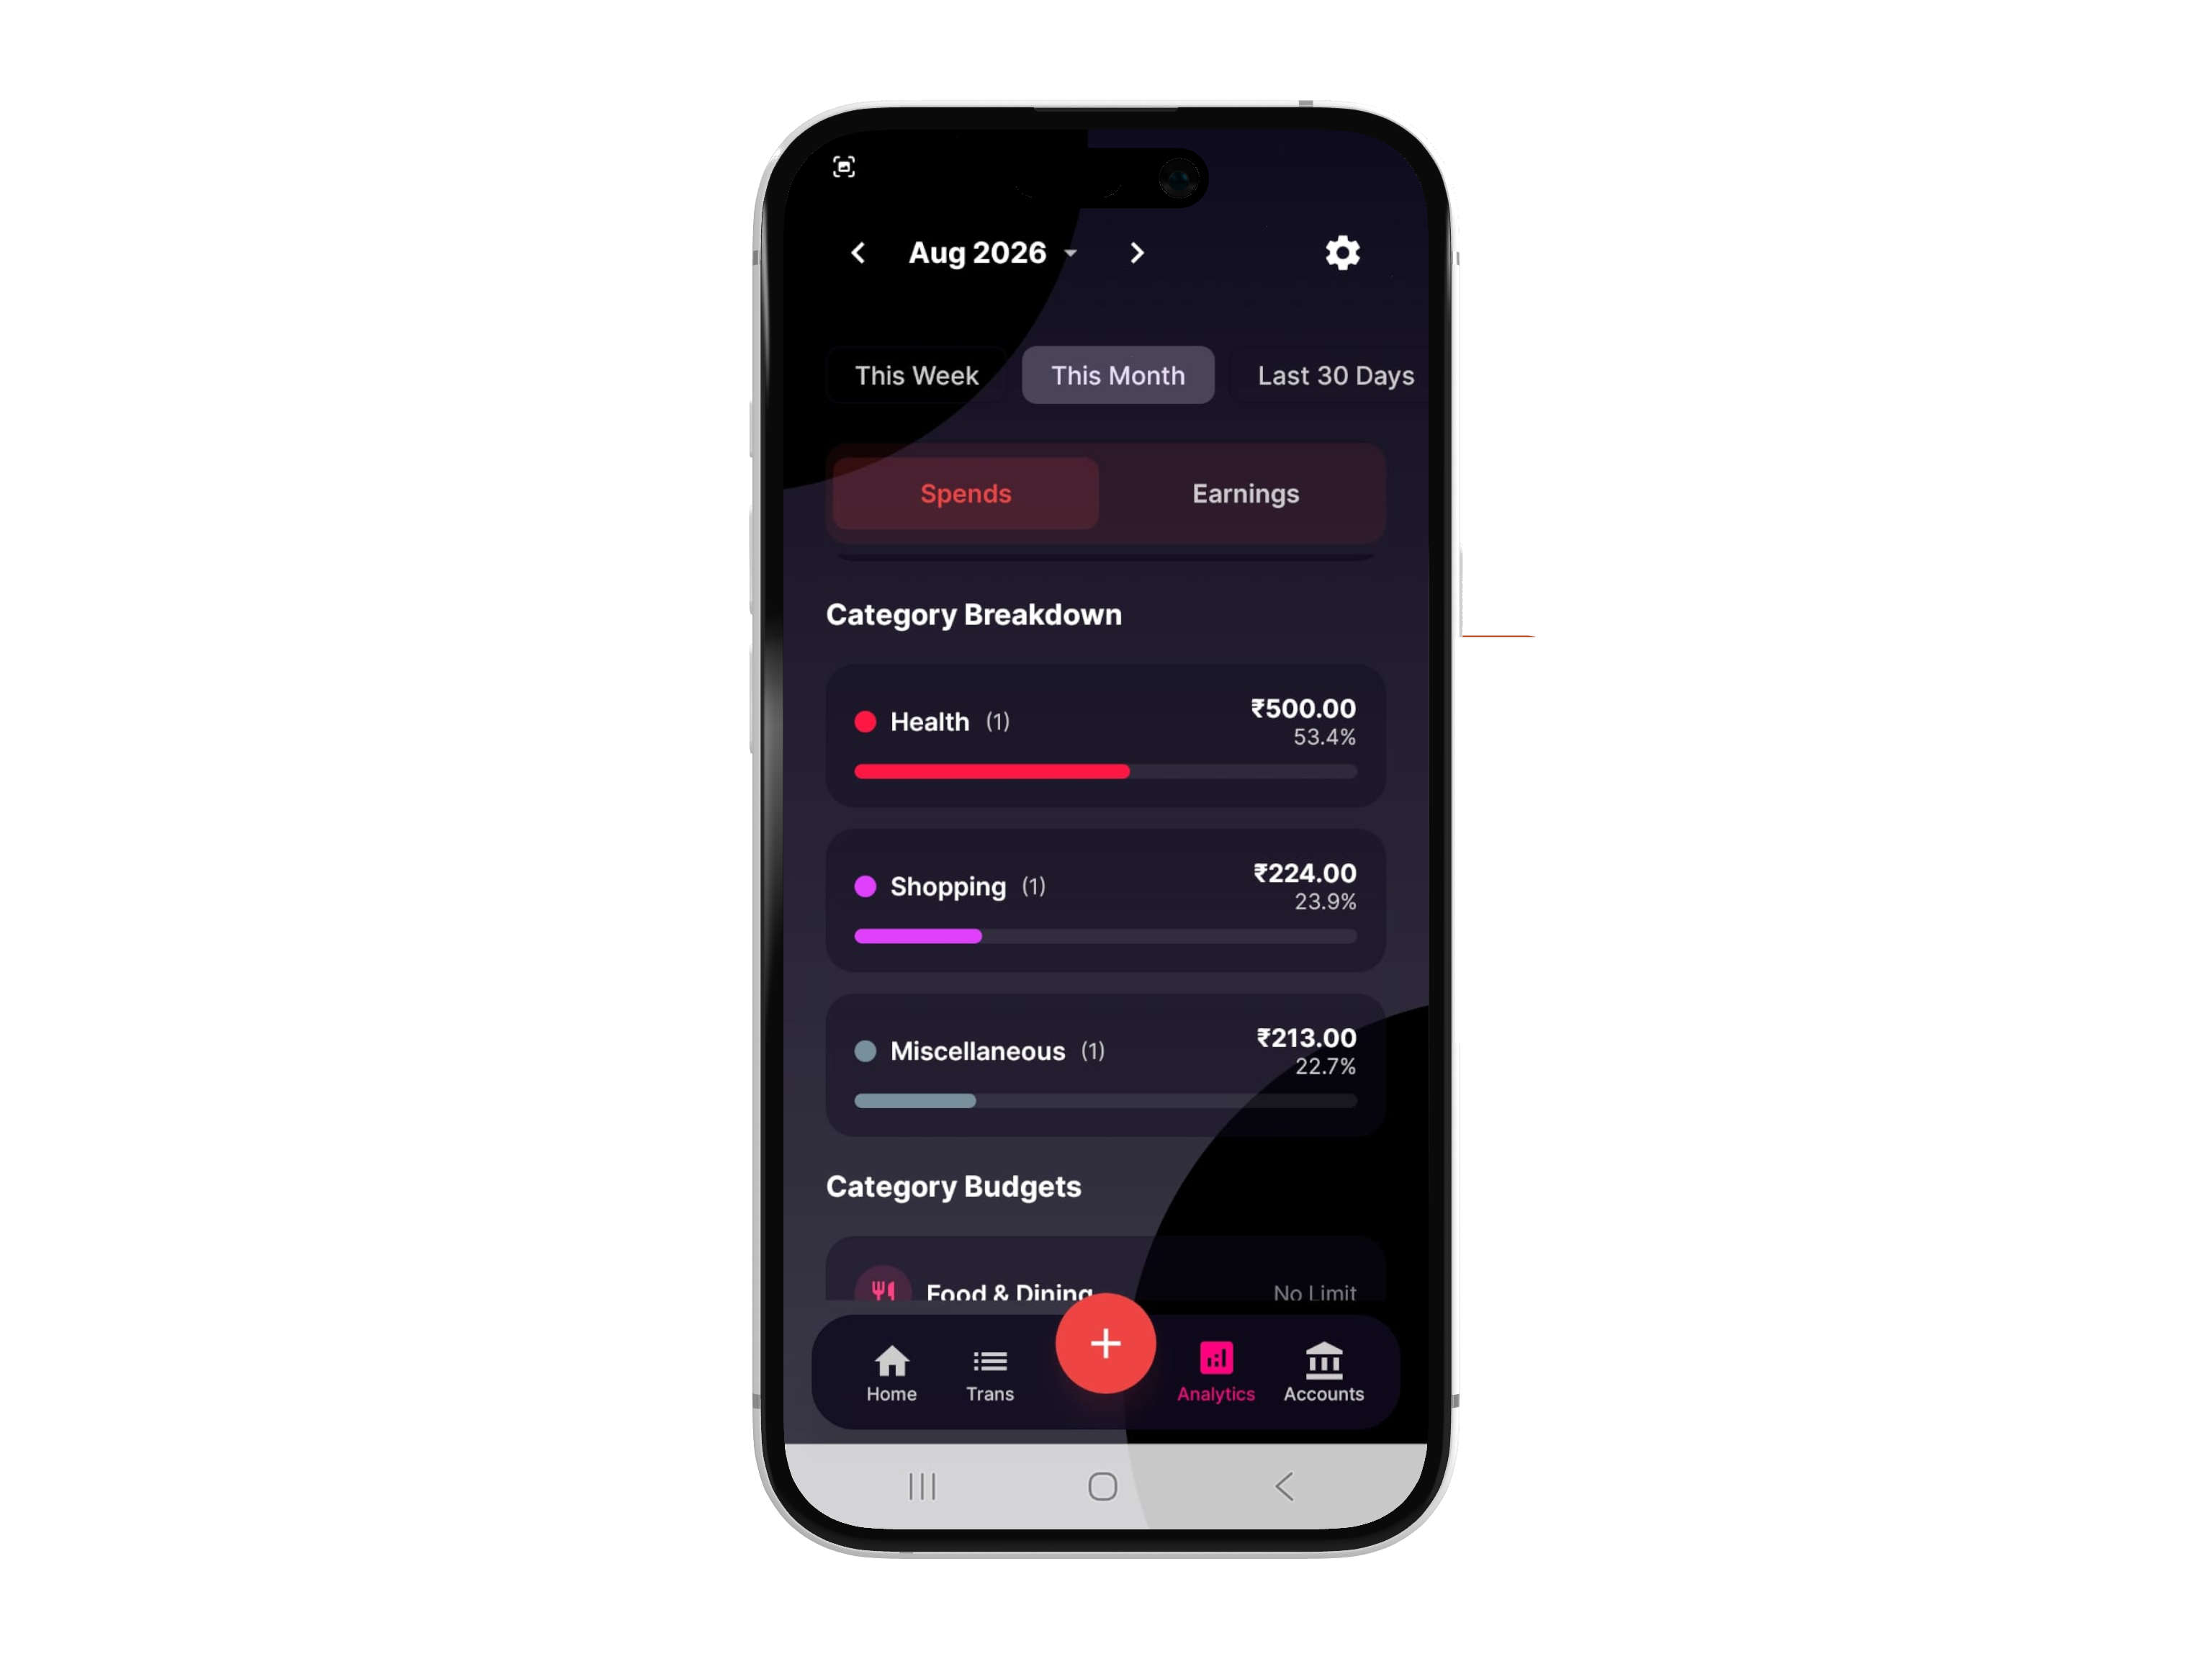
- Tap the Donut Chart: Drill into your top 3 expense categories for the week. Are food deliveries and impulsive e-commerce spikes creeping past 30% of total spend?
- Check your Achievements & Streaks: Celebrate sticking to your daily budget targets!
7. Stress-Free Tax Prep with PDF/Excel Reports
When financial year-end arrives in March, calculating deductions, donations (80G), medical expenses (80D), and business reimbursements usually turns into a weekend of frantic bank statement downloading.
Smart Money AI includes a native Excel and PDF Export Engine:
- Filter transactions by date range, account vault, or tax-relevant category.
- Export crisp, tabular spreadsheets with precise timestamp records.
- Hand them directly to your Chartered Accountant or finance team without editing raw personal statements.
8. Summary & Next Steps
Wealth accumulation is not about cutting out coffee or living on spreadsheets. It is about establishing frictionless visibility and boundaries:
- Automate ingestion so zero transactions slip through the cracks.
- Keep your financial privacy intact by eliminating third-party cloud servers.
- Use Safe Daily Spend limits to pace your lifestyle sustainably.
Start Your Private Wealth Journey Today
Experience automated UPI and multi-account tracking that runs 100% offline. Zero ads, zero accounts, true luxury.